South Africa has a growth story. Cape Town provides one.

I well remember when spectacular Clifton, on Cape Town’s Atlantic coast, served a very different residential community. Among their number were artists, writers and poets. Accompanying them were a few remittance men with a well-developed game of beach bats. Best played on a late summer evening. They lived modestly on land leased cheaply from the municipality. Upon which comfortable wooden bungalows, as we called them, were perched on the steep inclines. Life indeed was a beach for those who somewhat mysteriously had acquired valuable residential rights and easy access to brilliant sunsets.

And then the City did something very sensible. It offered the established residents the opportunity to convert their land leases into freehold at a very attractive rate. And rents and the value of renovated homes then began an upward spiral that continues to this day. And the locals mostly sold up and cashed in their windfalls to be replaced by the rich and not so famous.

The originals preferred not to sacrifice the rental income they would have done owner-occupying, or to delay realising their capital gains. They moved on to other less valuable locations and lower rentals. They traded off consuming what had become less expensive accommodation for more of the other necessities of life.  Consistently so given their limited incomes and overweight real estate. And the renovators, demolishers and builders moved in to satisfy those who could afford and consume more valuable homes on Clifton beach. Homes that have proved to be good investments that offset higher rentals and higher real estate taxes levied on the market value of the homes. And also providing a growing flow of revenue from rates levied on the market value of the Clifton Villas for the City.

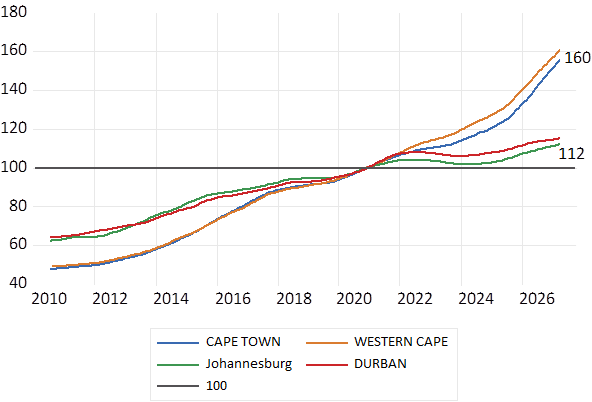
A Clifton type story is now evolving widely in Cape Town and environs. Where rents and property values have been rising and are expected to increase further. High rise real estate developments are well under way to meet the demand for space at rentals high enough to encourage developers and owners to speculate on increases in rentals to come.  Providing jobs and incomes way up the supply chain that includes the supply of labour. The average price of a home in Cape Town and the Western Cape has increased by 60% since 2020. In Durban or Johannesburg house prices on average have increased by only 12% since 2020.

Average House Prices in Cape Town, the Western Cape, Johannesburg and Durban. Monthly Data 2020=100
Source; Stats SA, Investec Wealth & Investment

There are however well recognised downsides to a successful City. More congestion for the established residents and visitors. And more strain to deliver water and electricity, refuse collection, roads and flyovers and to fight the fires. The other downside for those who do not own is more expensive accommodation for those who rent for cash. You could live a lot cheaper, rent at much lower rates per sq. metre, in Johannesburg and Durban. Or in the less expensive suburbs of Cape Town.

The answer to the growing scarcity of any good or service, including accommodation, is to increase supply. Build Baby Build. All who travel to inner Cape Town from the North or the South will notice that there is an abundance of undeveloped land close to the City. Turning that low or zero yield land into many more homes is surely possible. The City, by adding at its own expense, the infrastructure to connect vacant land to essential services, would help deliver increased supplies of land for building on.  Lower costs attached to land translates into lower prices for the buildings erected on them, given competition. The extra income collected every year from the rates to be charged on the additional housing stock would help re-cover such costs. Investing in infrastructure can provide good long term returns in kind and in cash for a growing City.

Property developments can be made more viable when higher permitted bulk is exchanged for additional so-called social housing as appears to be under way in Cape Town.  Accommodation supplied at a subsidised rental for those fortunate enough to win such a lottery. But a number questions need to be answered by social housing. The poor will not be able to afford even heavily subsidised rentals in high rise buildings that have to be well and expensively maintained. The essentially middle-income, or soon to become middle income teachers, health workers and administrators could qualify. But how will they be selected? And will they be permitted to do a Clifton? Rent out or sell up because it makes sense for them to spend less on what becomes expensive accommodation and more on the other essentials.

A successful City armed with a growing stock of taxable real estate can exercise choices with a budget that provides for improved amenities. That in turn add to property values. The tax revenue helps maintain the municipal capital stock and fund additional capacity to meet growing demands. Which supports and reinforces property values that then further improve flows of revenue. A virtuous circle made possible in Cape Town because it avoided being captured by its own officials. A fate suffered by many other SA municipalities.

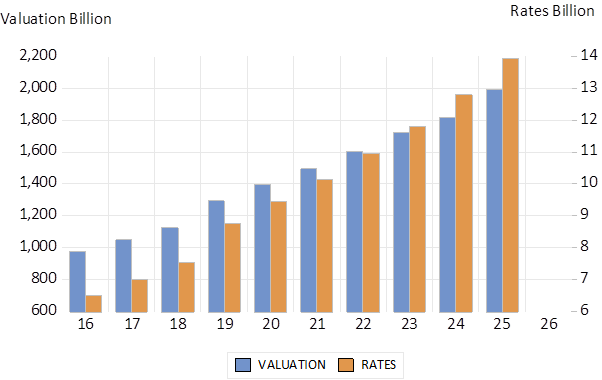
The value of taxed real estate in CT has been rising at an about seven per cent p.a. rate over the past ten years, more than doubling from about 1 trillion rand in 2016 to nearly 2.2 trillion rands in 2025. The average rate of the wealth tax on this property has been a consistently average (0.07%) per month-about 1.33% of property values per annum. Taxes collected on Property have been rising at about the same rate. Also more than doubling from R6.5 billion in 2015-2016 to R13.92 billion in 25-26. The City Budget expects R15.8 of income from rates in the 26-27 fiscal year an increase of 13.7%.

Cape Town-  Property Values (Left Scale) and Income from Rates (Right Scale) Annual Data R billions
Source; City of Cape Town Financial Statements and Investec Wealth & Investment

Cape Town can however be charged with spending and funding too conservatively. It should be encouraged to do more with its very strong balance sheet (minimal debt) and rising revenue streams and flows of cash. It could raise debt to add further to its infrastructure- in ways that would further reinforce property values and revenues. More boldness is called for.
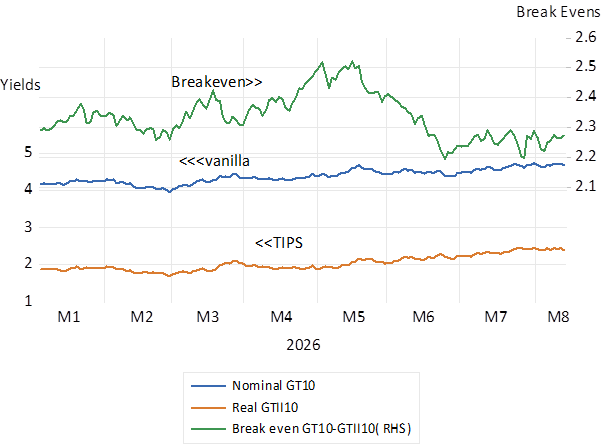
The Message from the Government Bond Markets – updated 13th August 2026

The Fed and the SARB surprised the markets after their recent meetings. The Fed by providing less forward guidance than was expected and the SARB by not raising short term interest rates. But still leaving expectations of higher short rates to come over the next twelve months largely unchanged. Long term bond yields in the US and SA immediately kicked higher but have since stabilised at higher levels in the US and returned to pre-meeting levels in SA.  The US market is currently pricing in a 58% chance of an increase in rates at its next meeting in September while in SA short rates are expected to be about a half a percent higher in twelve months. Expectations that in themselves are not helpful to the bond market.

This minor kerfuffle in the all-important US Bond market has come after a most extraordinary and extended period- since 2010 – sixteen and a half years – of poor returns – and returns more damaging to investors when compared to the excellent returns from US equities realised since then. Seldom if ever has a search for safety in the global bond and money markets been more expensive. In the form that is of extraordinarily good equity returns foregone. Between 2010 and July 2026 the S&P 500 realised an average annual return- capital gains plus dividends- calculated each month of 13.82% p.a. was realised. An index of US Treasury Bonds provided average returns of no more than 2% p.a. over the same period while cash delivered 1.5% p.a.

A realised equity risk premium of over 10 % p.a. is truly exceptional – and a rational reaction to bottom line index earnings growth that averaged over 11% p.a. over the same period. The exuberance of investors in publicly listed shares was justified by a growing bottom line. A case of valuations consistently catching up with underlying performance.  100 dollars invested in the S&P 500 in 2010 with dividends reinvested would have grown to 938 dollars by July 2026. The bond portfolio with interest reinvested in the Index would be worth only 138 dollars by now and a money market fund with interest reinvested in the money market is unlikely to be worth more than 130 dollars after 16 years. Understandable reasons for the risk averse to be crying in their cups.

What is helpful to shareholders – strong economic growth and increasingly profitable businesses- that are willing to invest heavily in future growth– all immediately growth encouraging – adds to the demand for financial capital – for savings – and will tend to raise interest rates. Especially when government fiscal deficits and bond issues are increasing – as they are in the US.

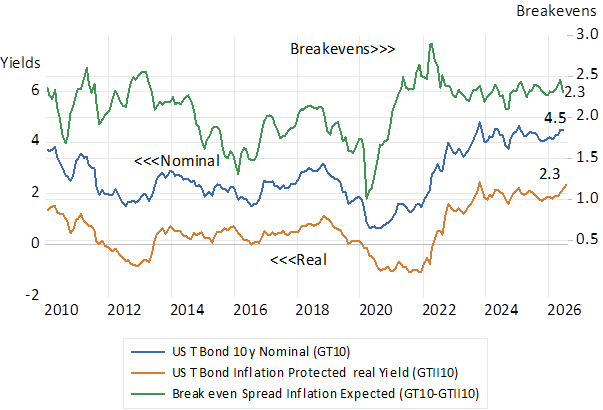
Bond yields in the US have risen recently not because more inflation is expected. Rather because more growth is expected to add to the competition for global savings. A competition that is well reflected in the higher real yields available to investors from low risk fully inflation protected US Bonds. The real yield on a 10-year inflation protected US Treasury Bond is now 2.3% p.a. – higher than at any time since 2010. By coincidence the breakeven yields are also currently 2.3%. That is the extra yield offered to investors in bonds exposed to the risk that inflation may rise unexpectedly. This spread can be regarded as an objective measure of inflation expected in the US over the next ten years. And is very close to the Fed target for inflation of 2% p.a.

Fig. 1; US Long Term Interest Rates- Nominal and Real 10 year Treasury Bonds –  and their Spread. Monthly data 2010-2026

Source; Bloomberg and Investec Wealth & Investment

Update to August 13th Daily Data – Yields trending higher- the RSA gives some more

The SA bond and money market provided much more competitive returns to investors since 2010. The difference between the JSE All Share returns and those of the bond and money market- the realised equity risk premiums- have been much more modest- of the order of 3-4 per cent p.a.  On average the share market has delivered average rand returns of 13% p.a.- compared to the ALBI Bond Index that delivered an average 9.2% p.a. on average and the money market that delivered 6.3% p.a. on average since 2010. A R100 invested in 2010 would have grown to R734 by July 2026, dividends reinvested, the Bond Index with interest reinvested would have compounded to R478 and a money market fund with interest ploughed back in the fund would be worth R282 by now.

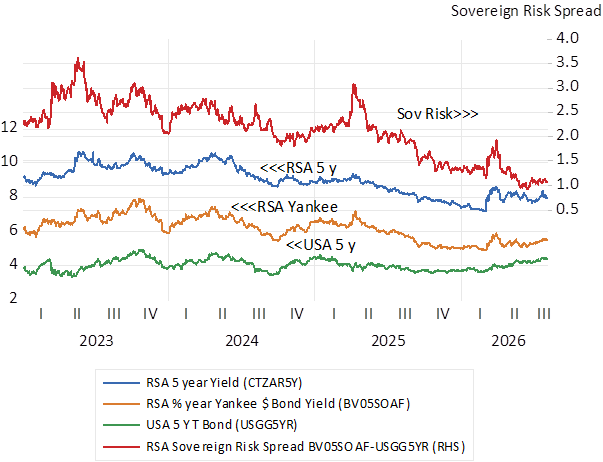
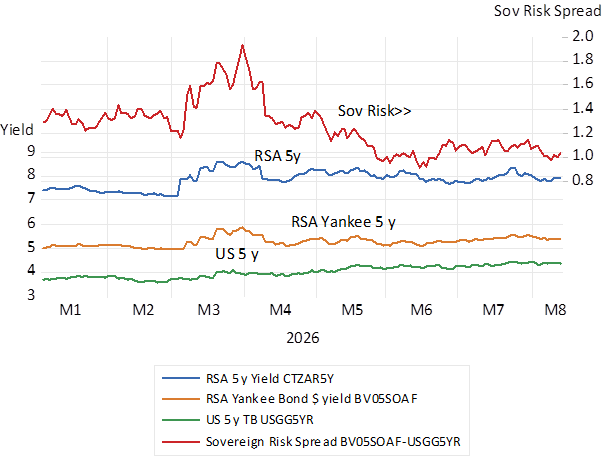
The performance of the RSA bond market since post-Covid 2023 and post the oil shock of March 2026 can be regarded as very helpful for the economy. Long term interest rates have come in and most important the spread between the cost to the SA taxpayer of borrowing dollars for five years rather than rands – the sovereign risk premium – has declined by 2% p.a since 2025 when the GNU was formed-to just over 1% p.a.. And declined further this year despite the oil shock. SA dollar denominated debt is now trading in the debt markets at close to investment grade.

Fig. 2: RSA Longer term Interest rates. 5 year bonds. Daily data

Source; Bloomberg and Investec Wealth & Investment

Daily Data 2026

Update- RSA doing well

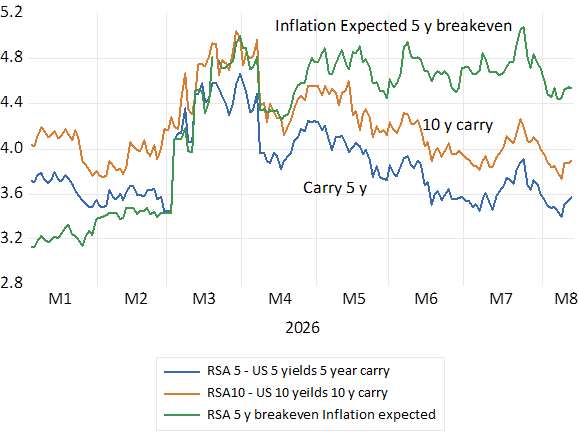
Daily Data;  July -August 2026. Inflation  expected over next five years(breakeven) still elevated- but lower recently as are the respective 5 year and 10 year carries. That is the expected value of the USD/ZAR is lower than it was. The ZAR has recovered strongly across the board. Outlook for inflation therefore declined.

How much more can the SA bond market offer investors? The answer will depend on the fiscal outlook for the SA economy. Will the fiscal deficits be well contained and the debt to GDP ratio continue to decline? If more economic growth were expected the answers would be affirmative in the best sense for interest rates.

The latest news from the fiscal front is now very encouraging. Tax revenues are rising significantly faster than expenditure. Perhaps an extra R90b of revenue this fiscal year ahead of the 2026-27 Budget is possible. Which if it materialises offers some growth and bond market encouraging possibilities. Possibly less to be borrowed and perhaps more adventurously providing capital for essential infrastructure improvements. But growth can only follow if the extra capital so employed can offer cost of capital beating returns. More capital with private sector partnerships, is essential to such purpose. And if expected to be sensibly practiced will add strength to the bond market and reduce the cost of capital to investors in SA. And in turn encourage more private capex to dd to the growth momentum.

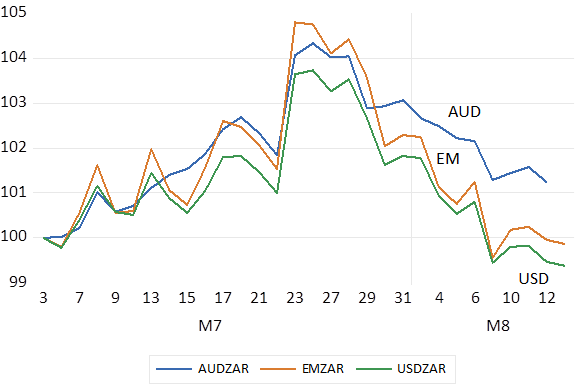
The mighty ZAR July =100. Daily Data

The rand rebounds strongly against the AUD, the EM Basket and the USD